Eugene Investment & Securities initiated coverage of Seobu T&D (KOSPI: 006730) on 15th October 2026, assigning a Buy rating and a target price of 19,000 won — implying 59% upside from the closing price of 11,950 won on 14th October.
Analyst Ryu Tae-hwan wrote that "development projects on sites held for many years are finally getting under way," arguing that investors should focus on the strong performance of the hotel business and the pre-sale revenues expected from upcoming developments.
The target price was derived using a sum-of-the-parts (SOTP) methodology, applying EV/EBITDA multiples based on global peer averages: 10.4x for the shopping mall, 15.8x for hotels, and 6.2x for the Corelle division. The present value of projected pre-sale profits from the Yongsan Najin Arcade and Sinjeong-dong Seobu Truck Terminal projects was then added to arrive at the overall enterprise value.
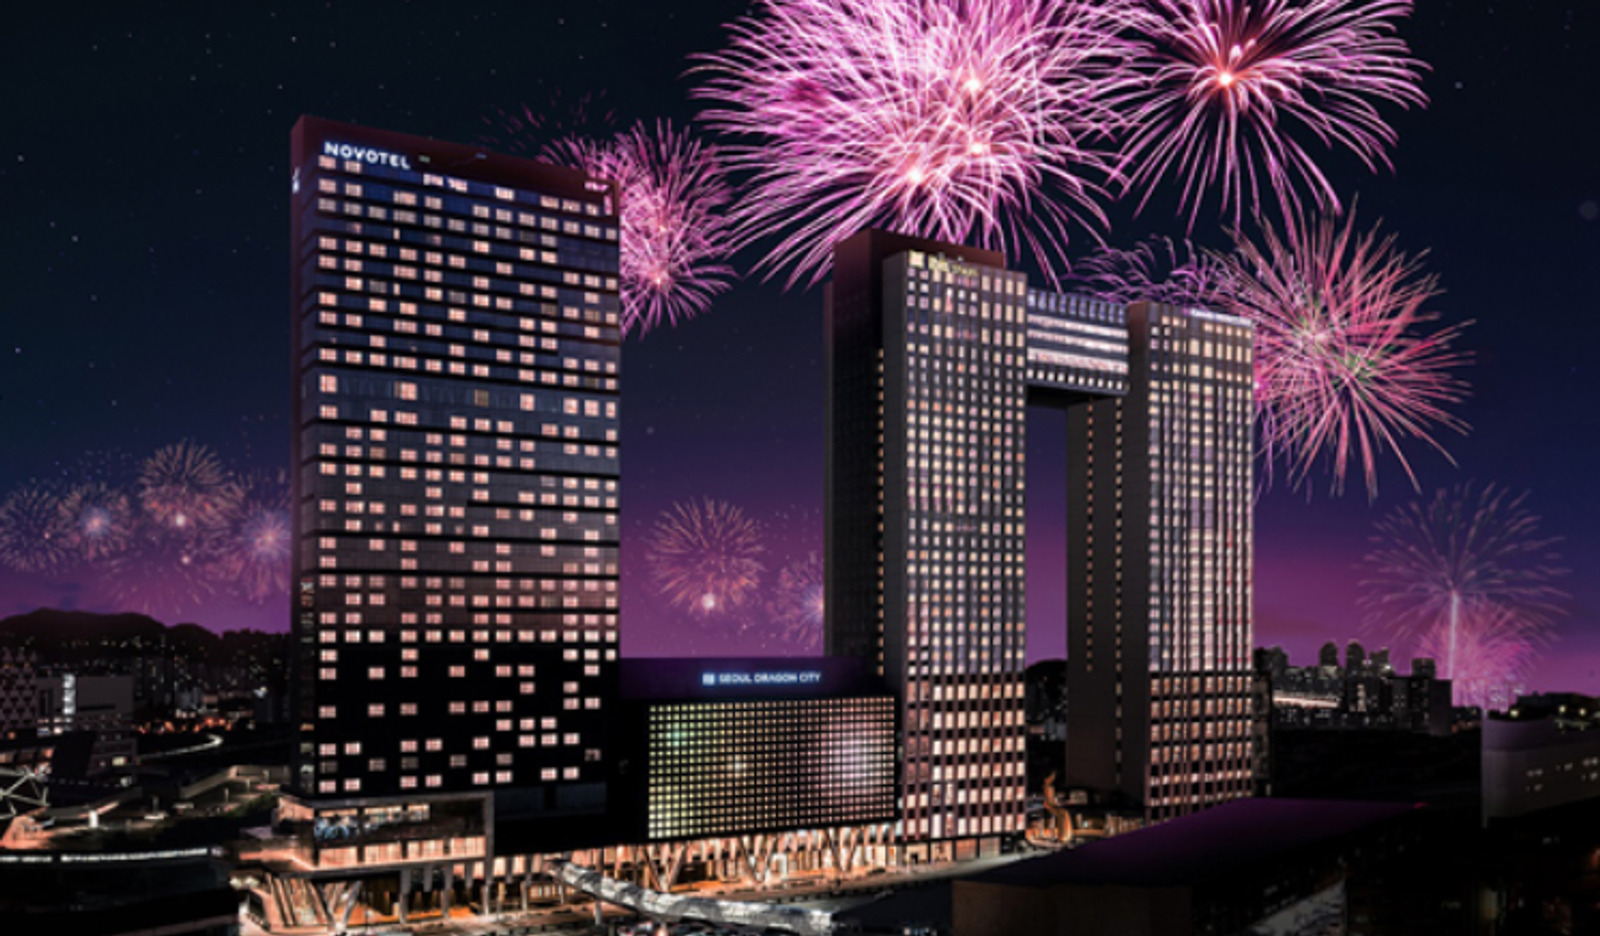
Seobu T&D is a property development and operating company that converted an Incheon freight terminal site into a mixed-use shopping mall (Square One) in 2012, and developed the former Yongsan International Ferry Terminal into a combined hotel and commercial complex (Seoul Dragon City) in 2017. Unlike pure hotel or retail operators, the company generates recurring operating income from assets it has developed directly.
Yongsan Najin Arcade Buildings 12 and 13: Construction Begins
One of the two flagship development projects broke ground on 8th October, following a capital expenditure disclosure of 624.1 billion won filed on 1st October. The site adjoins the Yongsan International Business District (YIBD) and will be developed into a mixed-use complex spanning eight basement levels and 27 above-ground floors, incorporating offices, serviced apartments (officetels), retail space, and sports facilities.
Eugene Investment & Securities estimates that, assuming a pre-sale price of 160 million won per pyong (approximately 3.3 square metres) of net floor area for the officetel units, total pre-sale revenue would reach around 520 billion won. Revenue recognition is expected to be spread over roughly 50 months, depending on the pre-sale rate and construction progress. Given the demanding price point, analysts have adopted conservative assumptions for the initial take-up rate.
The broader Yongsan area is transitioning from piecemeal plot-by-plot development to district-scale urban regeneration, which should support asset value appreciation. However, a unit price of 160 million won per pyong represents a significant demand hurdle, and the pace of initial pre-sales remains a key uncertainty for investors to monitor.
Sinjeong-dong Seobu Truck Terminal: April 2027 Ground-Breaking Targeted
The second major project — the redevelopment of the Seobu Truck Terminal in Sinjeong-dong, Yangcheon-gu, Seoul — is also advancing. Designated as a pilot urban advanced logistics complex by the Ministry of Land, Infrastructure and Transport in June 2016, the project has navigated a protracted permitting process, with final regulatory approval targeted for October 2026 and residential construction scheduled to commence in April 2027.
The scheme covers a combined-use site of roughly 20,030 pyong and a support-facilities site of approximately 9,456 pyong, and will incorporate logistics facilities, a shopping mall, and residential units. Of the 990 residential units planned, 892 are earmarked for open-market sale, with the remaining 98 designated as rental housing.
Based on surrounding property prices, Eugene Investment & Securities projects pre-sale revenue of approximately 1.4 trillion won, to be recognised over roughly 42 months. Demand resistance is expected to be lower here than at the Yongsan officetel scheme, given more accessible price levels. The combined present value of pre-sale profits from both projects is estimated at 30.3 billion won.
Hotel Business Driving Earnings Growth
Independently of the development pipeline, Seobu T&D's existing hotel operations continue to perform strongly. According to the Korea Tourism Organization, foreign visitor arrivals in August 2026 reached 2,245,000 — a record monthly high and a 23.3% increase year on year. Cumulative arrivals for January to August 2026 totalled 15.05 million, up 21.6%.
For the second quarter of 2026, hotel revenues at Seoul Dragon City rose 17.9% year on year to 50.4 billion won, while operating profit surged 39% to 17.1 billion won. The disproportionate earnings growth relative to revenue reflects the operating leverage inherent in hotel businesses: when occupancy rates and average daily rates rise simultaneously, the impact on profit is amplified by the sector's high fixed-cost base.
Eugene Investment & Securities forecasts third-quarter revenue of 88.1 billion won (+25.8% year on year) and operating profit of 26.4 billion won (+24.4%), implying an operating margin of 30.0%. Within that, hotel revenue is expected at 53.0 billion won (+18.0%) and the Corelle division at 25.8 billion won (+70.0%).
For the full year 2026, the brokerage projects revenue of 339.3 billion won (+36.6%) and operating profit of 91.8 billion won (+30.5%). As pre-sale revenues begin to flow through in 2027, earnings are forecast to expand sharply, with revenue reaching 502.1 billion won (+48.0%) and operating profit 141.2 billion won (+53.8%).
REIT Structure Offers Additional Value Unlock
Seobu T&D is the sponsor and largest shareholder of Shinhan Seobu T&D REIT, and operates an asset-recycling model under which income-producing properties are transferred into the REIT upon completion, allowing the company to recoup development capital. Non-residential assets from the Najin Arcade and Sinjeong-dong projects — such as offices, logistics facilities, and retail space — are expected to follow the same route once completed, though the timing and terms will depend on rental income stabilisation and conditions in the REIT financing market.
Separately, the Ninetree Hotel Dongdaemun, a REIT-held asset, was sold in April this year. A special dividend based on the proceeds is expected at the REIT's December 2026 year-end (its 13th fiscal year), from which Seobu T&D, as a principal unitholder, stands to receive additional dividend income.
Financial Leverage: A Risk to Watch
Some market observers flag the financing burden as a meaningful risk. Total borrowings at end-2026 are estimated at 1.352 trillion won, with net debt of 1.188 trillion won — implying a net debt-to-equity ratio above 81%. As the two development projects advance, total borrowings are projected to reach as high as 1.767 trillion won in 2027–28. Pre-sale performance will therefore be the critical variable for financial stability, making early progress on sales a closely watched indicator for the investment case.