SK Securities reiterated its buy rating and 2,000,000-won price target on Samsung Biologics (KRX: 207940) in a report published on 6th October 2026, forecasting that the company's third-quarter results would broadly meet market expectations despite a costly labour dispute and currency headwinds.
Analyst Lee Sun-kyung estimated third-quarter consolidated revenue of 1.374trn won, up 9.3% year on year and 4.0% quarter on quarter, with operating profit of 609.8bn won, yielding an operating margin of 44.4%. That represents a year-on-year decline of 3.7% in operating profit, but comes in 2.2% and 0.7% above the market consensus of 1.345trn won in revenue and 606.3bn won in operating profit, respectively.
The year-on-year profit dip reflects two exceptional burdens. A strike in May disrupted production of roughly 20 batches, crystallising cost losses of approximately 150bn won. Separately, the won strengthened by around 5% against the dollar compared with the previous quarter, squeezing margins on dollar-denominated contracts. The comparison base is also demanding: in the third quarter of 2025, Samsung Biologics posted an operating margin of 50.4%.
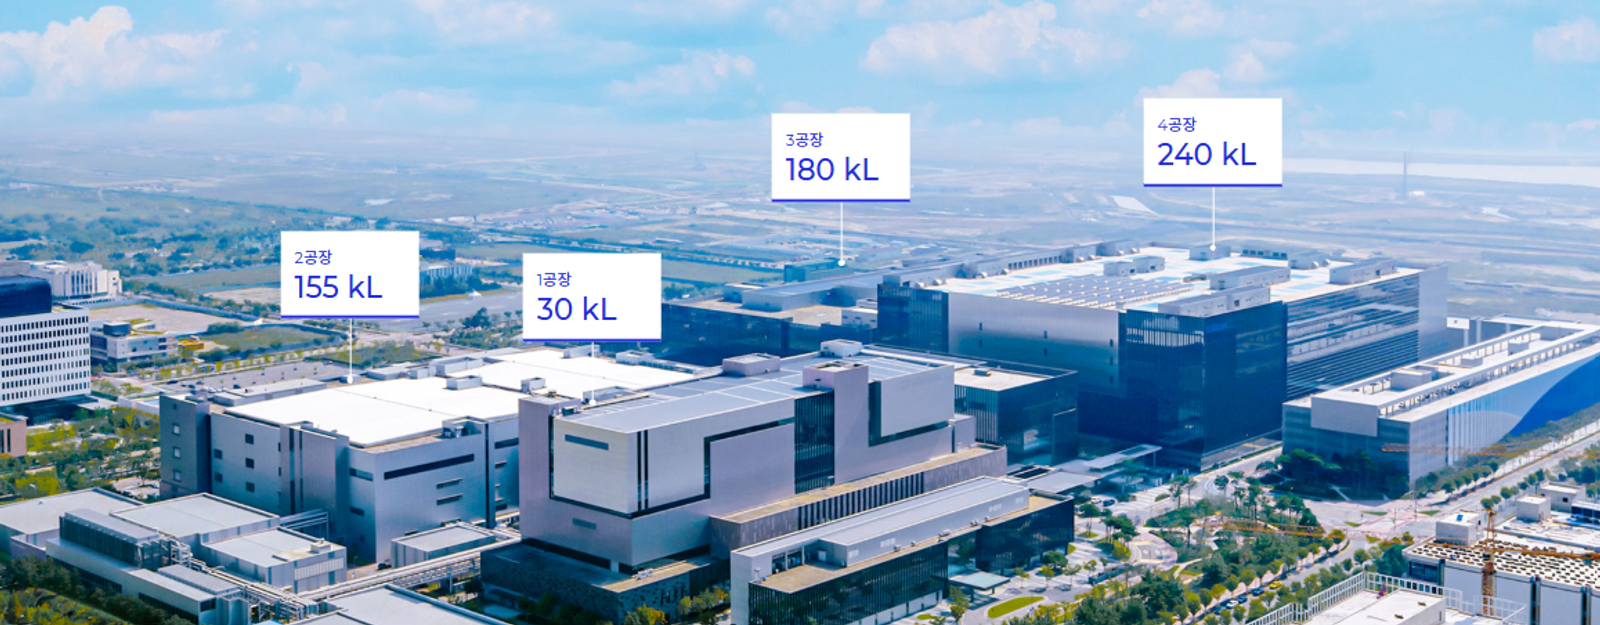
Partly offsetting these pressures, revenue contributions from the fifth manufacturing plant — which began process performance qualification (PPQ) batches — and from the company's newly acquired American facility are both being recognised for the first time this quarter, supporting top-line growth. The 150bn won in production delayed by the strike is being rescheduled for shipment in the fourth quarter after coordination with clients, providing a potential boost to revenues later in the year.
For the full year 2026, SK Securities forecasts revenue of 5.447trn won and operating profit of 2.424trn won, implying operating profit growth of 17.2%. That is less than half the 56.6% operating-profit growth Samsung Biologics achieved in 2025, when the company reported annual revenue of 4.557trn won and operating profit of 2.068trn won. Beyond the strike and the currency drag, the acquisition of Polypeptide Group — a peptide-focused contract drug manufacturer — is also weighing on near-term accounting metrics.
New order momentum is a further concern. Cumulative contract manufacturing (CMO) orders stood at $21.7bn as of the first half of 2026, but net new orders in the period amounted to just $500m — a sharp retreat from the $4.9bn in new business won during 2025. SK Securities attributes the slowdown to uncertainty surrounding potential US Section 232 tariffs on pharmaceutical imports, which cooled outsourcing discussions among global drugmakers. With the administration having announced its Section 232 decision in April, the broker believes contract negotiations are now recovering and that further new orders are possible before year-end.
Looking further ahead, the growth case rests on three pillars. The fifth plant is ramping up, with its revenues now beginning to flow through in earnest. The American facility in Rockville, Maryland, acquired in the first quarter for $353m, gives Samsung Biologics a dual-continent manufacturing network; its current capacity of 60,000 litres can be expanded to 100,000 litres. The pending acquisition of Polypeptide Group, expected to close before year-end, adds a peptide-based CDMO capability. Polypeptide's target EBITDA margin of 25% by 2028 trails Samsung Biologics' own 44%-plus margin, but analysts see room for improvement given the strong structural growth of the peptide CDMO market.
One near-term overhang for shareholders is a rights issue announced on 28th August, under which Samsung Biologics will issue 2.77m new shares — equivalent to a 4.9% capital increase. The issue price was revised down from an initial 1,322,000 won to 1,174,000 won per share, with new shares scheduled to list on 30th November. The resulting dilution adds to the list of short-term concerns.
At 1,354,000 won as of 2nd October, the share price sits roughly 30.6% below its 52-week high of 1,949,875 won, reflecting the cumulative effect of the strike, currency appreciation, weak new orders and the equity issuance. SK Securities calculates upside of 47.7% to its 2,000,000-won price target, with market capitalisation standing at 62.678trn won. Whether the stock can reclaim lost ground is likely to depend less on the absolute level of earnings and more on whether new-order momentum and margin recovery can persuade investors that the company's growth trajectory remains on course.