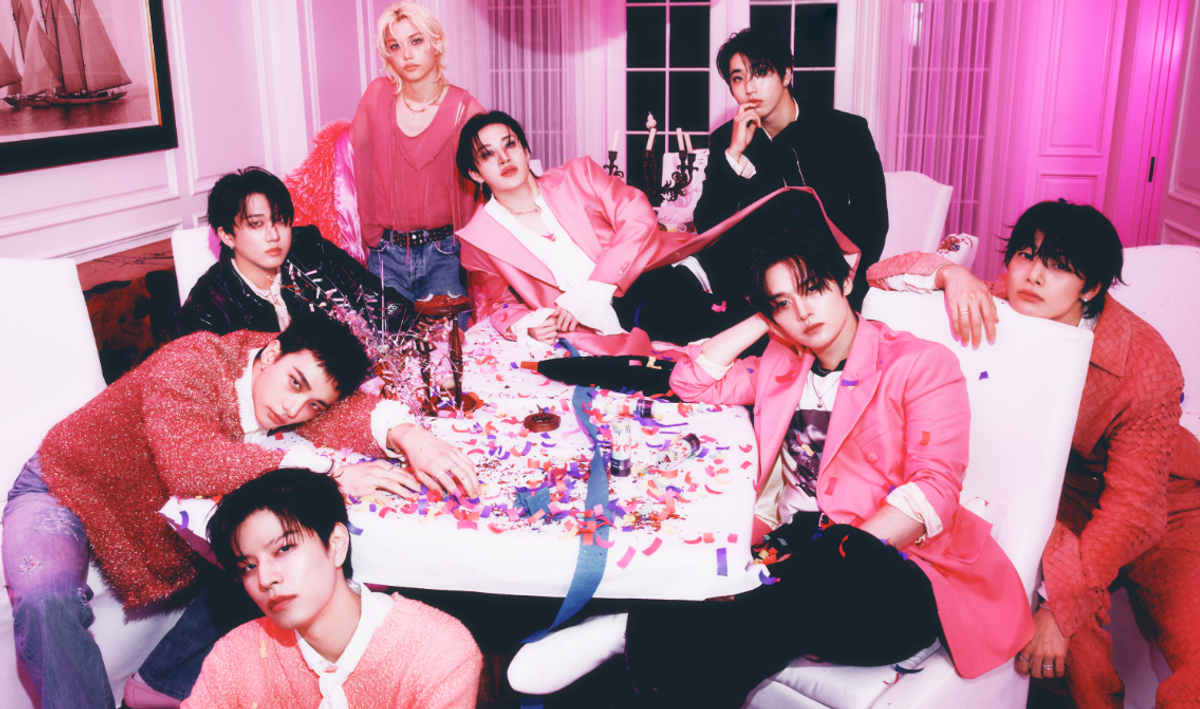
SK Securities reiterated its buy recommendation on JYP Entertainment (KOSPI: 035900) on the 22nd, keeping its target price at 66,000 won. The brokerage expects the second half of the year to be driven by Stray Kids' new album release and the launch of their "RUN IT" world tour.
SK Securities forecasts JYP Entertainment's 2026 revenue at 866.5bn won, up 5.2% year on year, with operating profit of 163bn won, a 5.0% increase, implying an operating margin of 18.8%. These figures represent a modest improvement on the 2025 estimates of 821.9bn won in revenue and 155.2bn won in operating profit. The current target price of 66,000 won, however, already reflects two rounds of cuts — down from 92,000 won in March and 75,000 won in July — and sits 71.4% above the current share price of 38,500 won, a gap that cuts both ways.
Stray Kids: K-pop's unlikely arena act
Stray Kids released their tenth mini-album, *This & That*, on 7th August. First-week sales reached approximately 3.3m copies, more than 1m ahead of their previous mini-album, *ATE*. By Billboard's reckoning, the group ranked tenth in global artist tour revenue in 2025, generating $185.7m from 31 shows attended by 1.3m fans — the only K-pop act to feature alongside Western pop headliners. Coldplay topped the list at $464.9m, but the comparison alone signals how far Stray Kids have travelled from their origins as a niche act.
The "RUN IT" world tour has so far announced only its first leg, covering three cities across South Korea and Asia for 18 shows. Western dates have yet to be confirmed. SK Securities believes that once a Western leg is added, the tour could extend into the first half of 2027. Beyond concert revenue, the group's character intellectual property, SKZOO, is being rolled out via an expanding series of global pop-up events, offering a secondary stream of merchandise income.
Twice: a fading certainty
JYP's other flagship act, Twice, concluded their "THIS IS FOR" world tour — which began in July last year — with a Seoul encore run in July 2025. The tour was notable for pioneering a city-linked pop-up format, which proved effective at lifting merchandise sales and is now being extended to other acts on the label's roster. Yet the tour's conclusion also marked the departure of two members, Jeongyeon and Chaeyoung, from the agency. A full reunion of the original nine-member group is now uncertain.
Two gaps at once
JYP Entertainment now faces simultaneous uncertainty around both of its mega-franchises. Twice's return as a complete group is in doubt; Stray Kids carry a potential disruption of their own in the form of military service obligations for members Bang Chan and Felix. That said, both hold Australian nationality and are not subject to South Korea's conscription requirements, meaning the group can sustain activity through solo and sub-unit work even if the full lineup is temporarily incomplete.
Younger acts stepping up — or not yet
Whether JYP's newer acts can fill the gap will be critical. NMIXX completed their first world tour this year, marking a transition into commercially meaningful territory. The pace at which NexZ and Xdinary Heroes (Kickflip) scale up will determine how well the company weathers any prolonged absence from its established headliners.
Merchandise rising, concerts dipping
The detailed financial picture shows diverging trends across revenue streams. Merchandise sales are forecast to grow more than 30% in 2026, reaching 245.4bn won from 188.5bn won in 2025. Concert revenue, by contrast, is expected to fall to 171.8bn won in 2026 from 188.9bn won this year, as Stray Kids only partially offset the absence of a Twice tour. A recovery to 207.9bn won in concert revenue is projected for 2027, contingent on Stray Kids expanding into Western markets.
Risks worth heeding
Investors should weigh several concerns. SK Securities' own target-price trajectory — from 92,000 won in March to 75,000 won in July to 66,000 won in August — reflects a steady recalibration of expectations. The current share price of 38,500 won is less than half the 52-week high of 85,000 won. A wide gap between the target and market price can signal upside potential, but it can equally reflect a market that has lost confidence in the underlying earnings story.
Broader structural risks persist: a slowdown in physical album sales across the K-pop industry, a delayed recovery in Chinese demand, and currency volatility that complicates overseas revenue. Most tellingly, SK Securities' own projections show revenue and operating profit in 2027 — at 860.8bn won and 146.9bn won respectively — edging slightly below the 2026 figures, suggesting the firm does not yet see a sustained growth trajectory resuming in the medium term.