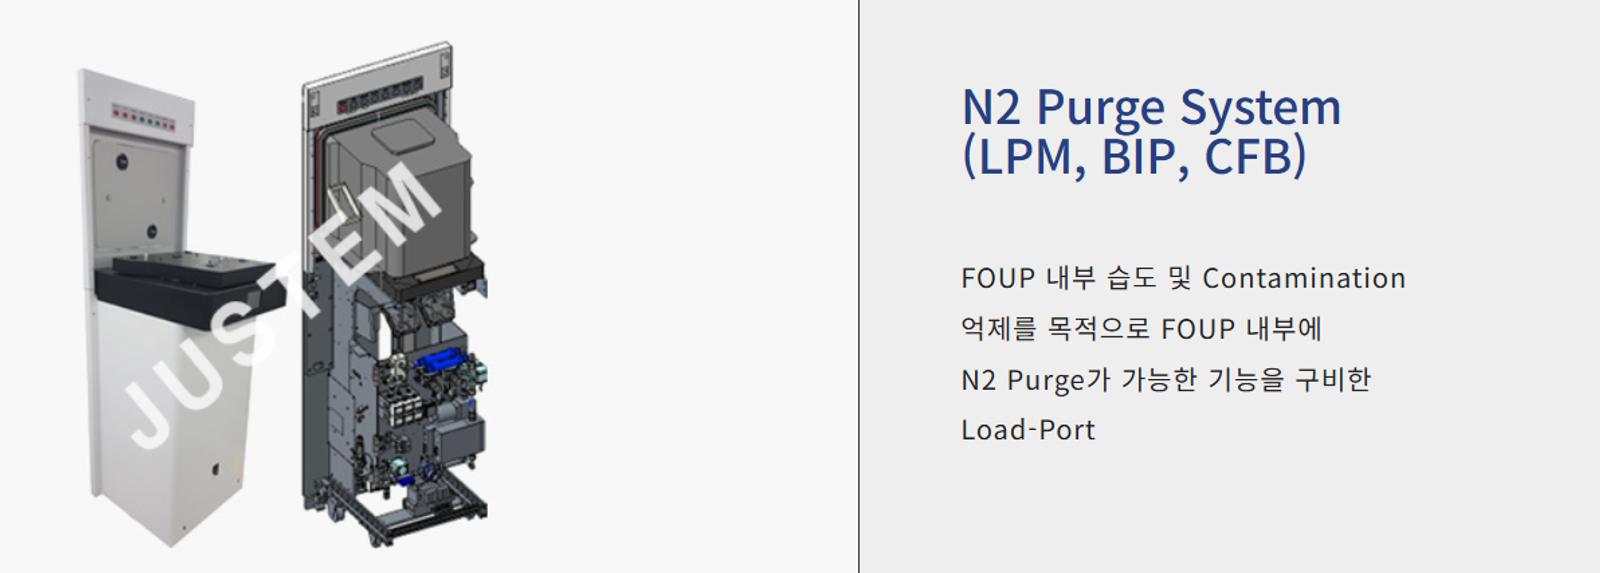
iM Securities on July 12th initiated coverage of Justem (KOSDAQ: 417840), a specialist in humidity-control solutions for semiconductor manufacturing, predicting that the company will set successive all-time profit records in 2026 and 2027 as global memory chipmakers ramp up capital expenditure.
From loss-making to record profits in two years
The broker's research division estimates Justem will generate revenues of 113.3 billion won and operating profit of 32.6 billion won in 2026, rising to revenues of 151.6 billion won and operating profit of 50.5 billion won in 2027. The trajectory of these figures is striking when set against the company's recent history. Justem recorded revenues of just 35.9 billion won and a paper-thin operating profit of 300 million won in 2023, before slipping into a 4.6 billion won operating loss in 2024 on revenues of 38.7 billion won. A recovery in 2025 — revenues of 48.3 billion won and operating profit of 4.6 billion won — marked a return to the black, but iM Securities' 2026 revenue estimate represents a 134.6% jump on that already-improved base. In short, a company that was losing money two years ago could, if the broker's analysis proves correct, be earning more than 30 billion won in annual operating profit within two years.
Order book signals confidence
The forward order book lends some credibility to these projections. Annual new orders have risen steadily, from 31.7 billion won in 2023 to 38.9 billion won in 2024 and 54.4 billion won in 2025. More tellingly, cumulative new orders for the current year had already reached 71.8 billion won by 30th June — surpassing the whole of last year's total in just six months. The backlog at that date was estimated at more than 40 billion won, providing a solid foundation for accelerating second-half performance, the report argues.
The surge in orders reflects large-scale procurement from Samsung Electronics' Taylor, Texas foundry and from Micron's operations in the United States, Taiwan, and Japan. As memory chipmakers invest simultaneously in expanding production capacity and improving manufacturing yields to meet demand for DRAM and high-bandwidth memory (HBM) chips, Justem's nitrogen (N₂) purge-based humidity-control systems are capturing a growing share of that spending.
What Justem actually makes
Founded in 2016, Justem specialises in N₂ purge systems that remove moisture and contaminants during the transport and storage of semiconductor wafers. Its principal products are Load Port Modules (LPM), the Justem Flow Straightener (JFS), Built-In Purge units (BIP), and Contamination-Free Buffers (CFB). As of the second quarter of this year, LPM accounted for 75.9% of product revenues, followed by JFS at 11.3% and BIP at 9.3%. Its three core customers are the world's leading memory chipmakers: Samsung Electronics, SK Hynix, and Micron.
A particular source of medium-term optimism is the JFS, the company's second-generation product. Unlike the LPM, the JFS can be retrofitted as an add-on to existing first-generation production lines. At present, JFS penetration among lines already fitted with first-generation LPM units stands at only around 8%, leaving 92% of the installed base as a potential source of incremental revenue. By end-2025, Justem's cumulative product revenues had reached 260.1 billion won (of which export revenues totalled 106.6 billion won), and the company has reportedly supplied more than 1,500 systems to Micron alone.
Risks worth heeding
Investors should note, however, that this analysis represents the view of a single brokerage. Several risk factors warrant attention.
Customer concentration is the most immediate concern. In the first half of 2026, two clients — identified only as Company B (50% of revenues) and Company C (23%) — together accounted for 73% of total sales. Should either reduce investment spending, earnings volatility could be severe. This is not merely a theoretical risk: in 2024, a single customer (identified as Company E) saw its share of Justem's revenues collapse from 23% to 6%, dealing a significant blow to group profitability.
The cyclical nature of the memory chip industry adds a further layer of uncertainty. The sector is notorious for sharp, rapid swings between over-supply and under-investment. Justem's lean years of 2023–24 were themselves partly a product of such a downcycle. The current boom in HBM demand is pulling memory investment higher across the board, but how long this upcycle lasts remains genuinely unclear.
Finally, the share price already reflects a good deal of optimism. Justem's shares closed at 15,720 won on 8th October, roughly four times their 52-week low of 3,159 won, and the absolute return over the past 12 months stands at 223.5%. The company's market capitalisation is approximately 36.1 billion won. Applying iM Securities' earnings estimates, the shares trade at 13.0 times 2026 forecast earnings and 8.5 times 2027 forecast earnings — valuations that leave little room for disappointment if results fall short.
iM Securities has assigned Justem a Not Rated (NR) designation, offering no target price.