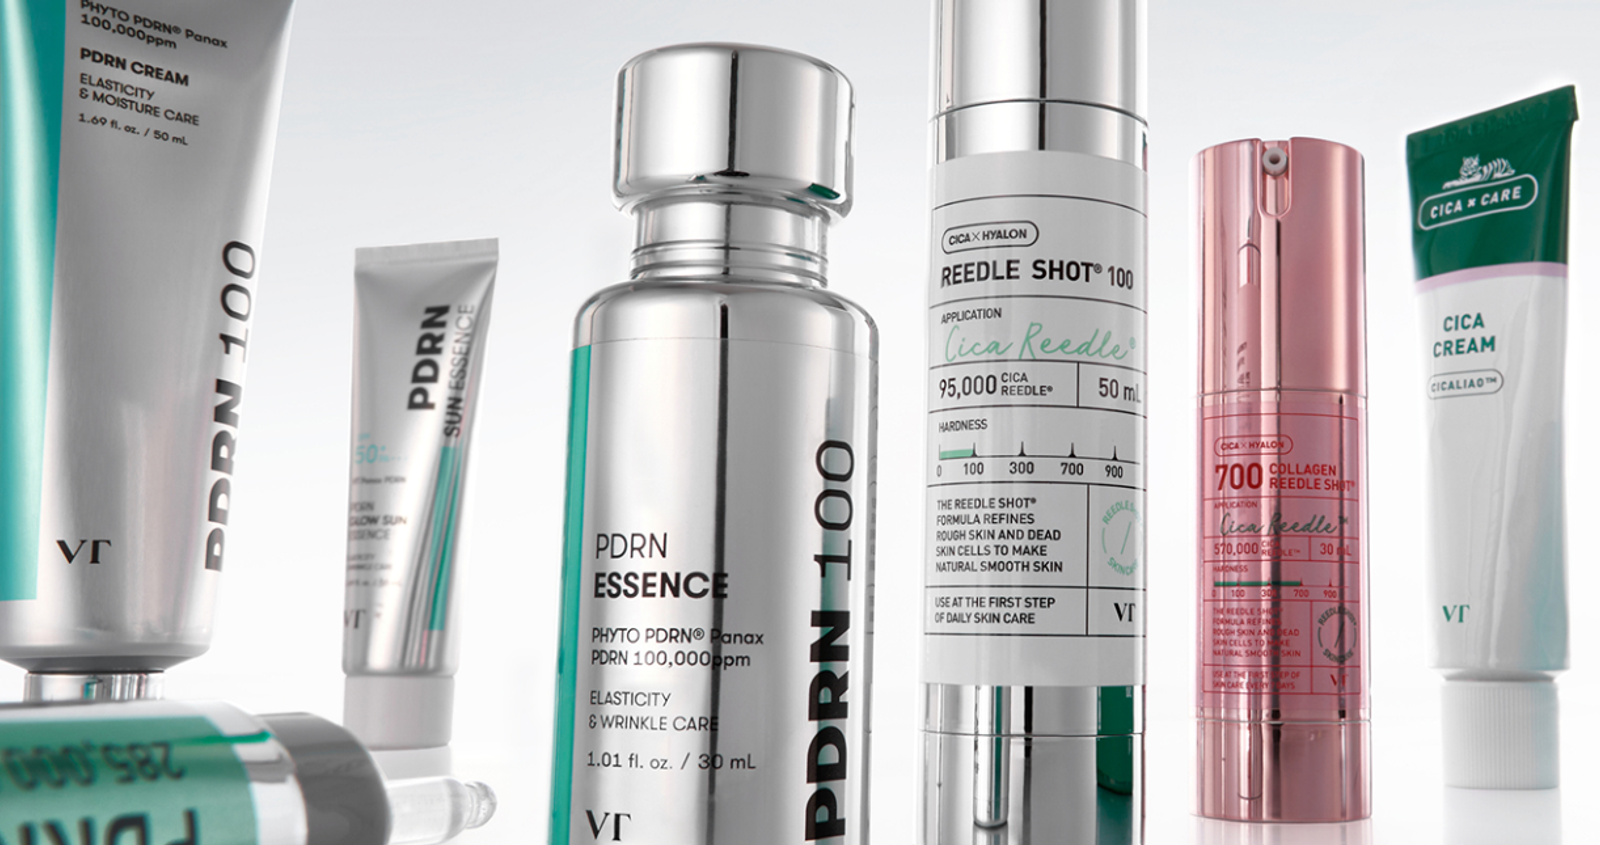
In a company visit report published on 8th October, IBK Investment & Securities analysed VT (KOSPI: 018290), concluding that the K-beauty firm is actively reducing its dependence on Japan and broadening its sales channels into North America, Europe and Russia. The brokerage also noted that VT's PDRN skincare line is rapidly emerging as the next growth engine to succeed its flagship Reedleshot product.
Japan: from pillar to problem
VT began targeting Japan in earnest from 2021, lifting the country's share of total revenue to roughly 40% by 2024–25. That concentration has since become a liability. Intensifying competition among K-beauty brands, insufficient consumer understanding of how to use Reedleshot correctly, and the ageing of VT's original Cica line have combined to push Japanese sales into decline. Japan's revenue share has now fallen to around 25–26%.
There are, however, tentative signs of stabilisation. Sales data for Cica and Reedleshot products in Japan began to show a recovery from May–June 2026, and VT's performance in the third-quarter Qoo10 Mega Sale event — a major promotional occasion on one of Japan's leading e-commerce platforms — showed sequential improvement in yen terms. IBK Investment & Securities argues that, with Japan's revenue share already compressed to 25–26%, the scope for further decline is limited. Should Japanese sales stabilise, the rapid growth being generated elsewhere could translate more directly into group-level revenue acceleration.
PDRN: the next hero product?
A clear shift is also under way in VT's product portfolio. The PDRN line, launched in the third quarter of 2025, has grown sharply across domestic and international channels in 2026 and is establishing itself as the successor to Reedleshot. At Daiso — Japan's ubiquitous discount variety chain, which has a significant presence in South Korea — PDRN-related sales rose from approximately 6 billion won in the first quarter of 2026 to roughly 7.8 billion won in the second quarter, with a PDRN tone-up sub-line added in the third quarter. Because Daiso requires minimal advertising and promotional expenditure compared with other retail channels, it is regarded as a relatively profitable outlet even after accounting for tighter unit margins.
In North America, a PDRN essence duo pack generated around 3 billion won in revenue at Costco in the second quarter of 2026. A bundled Reedleshot product sold out and is expected to generate a reorder worth approximately 2–2.5 billion won in the third quarter of 2026. PDRN sales are also expanding in Russia, extending VT's reach across both new geographies and new channels simultaneously.
Regional growth: Russia, Europe, the Middle East
The pace of expansion across individual markets is striking. In Russia and the broader CIS region, quarterly revenues grew from an initial 1–2 billion won following VT's entry into Gold Apple — a prominent Russian beauty retailer — in the third quarter of 2025 to approximately 7.5 billion won per quarter by 2026. In Europe, revenues rose steadily from 4 billion won in the fourth quarter of 2025 to 5 billion won in the first quarter of 2026 and 7 billion won in the second quarter, with single orders from local distributors such as Notino and Dermaspace reaching 1–1.5 billion won. In Turkey, a large order worth roughly 3 billion won was placed through the Gratis retail chain in the second quarter of 2026, with monthly revenues subsequently running above 1 billion won. VT is also expanding into key Middle Eastern markets including Saudi Arabia, the UAE and Lebanon.
In North America, VT's strategy follows a deliberate online-to-offline sequencing: building a consumer track record on Amazon and TikTok Shop before pushing into bricks-and-mortar retail through Ulta Beauty and Costco. Talks with Walmart are under way. Notably, consumer response has proved stronger at Costco than at Ulta, which had initially attracted higher expectations.
Growth at a cost
Management has guided for second-half revenues to exceed the first half by roughly 25%. On a full-year basis, consensus forecasts put revenue at 437.2 billion won for 2025 rising to 522.1 billion won in 2026. Yet operating profit is expected to move in the opposite direction, falling from 82.9 billion won in 2025 to 60.3 billion won in 2026. The operating margin is forecast to compress sharply, from 19.0% to 11.5%.
The culprit is the cost of global expansion. As VT pushes into overseas markets — particularly through online business-to-consumer channels such as Amazon and Shopee — advertising and promotional spending has risen by approximately 20 billion won, while logistics, warehousing and platform commission costs have climbed by a further 15 billion won. Online channels carry heavy fulfilment costs, local delivery charges and sales commissions that limit profit leverage relative to revenue growth. A telling precedent comes from Shopee, where VT's online-to-offline ratio shifted from 80% online towards 40% offline, at which point profitability improved materially. IBK Investment & Securities expects a similar channel-mix improvement in North America and Europe to ease commission and logistics burdens over time.
Three tests for investors
IBK Investment & Securities identifies three key questions that will determine VT's investment case. First, whether the tentative recovery in Japanese sales data since May–June represents a genuine, sustained trend or merely a temporary fluctuation. Second, whether PDRN can establish itself as the next flagship product. Reedleshot built a competitive moat through VT's full in-house control — via subsidiary E&C — of spicule quality and formulation expertise, a key raw material in the product. PDRN, by contrast, is still in the early stages of market validation. Third, how quickly VT can restore profitability by shifting towards offline channels.
The brokerage's base case is that if Japanese sales stabilise and the offline share of revenues rises in tandem, 2027 could see revenue growth and margin recovery proceed in parallel. That is, however, an optimistic scenario from a single broker. Competition in global K-beauty is intensifying, and the structural risks of dependence on single channels or trend-driven hero products are not unique to VT — they are a challenge for the sector as a whole. The strategic direction of diversification, both by product and by geography, is sound. But the speed of cost discipline and profit recovery will ultimately be what matters most to investors.