Mirae Asset Securities reaffirmed its buy recommendation on Hyosung Heavy Industries (KRX: 298040) on 13 October 2026, while trimming its 12-month target price by 12% from ₩5m to ₩4.4m per share.
Near-term earnings disappoint
The downgrade in target price reflects a more cautious view of third-quarter results (July–September 2026). Mirae Asset now forecasts quarterly revenue of ₩1.7438tn, up 7.4% year on year, and operating profit of ₩281.6bn, up 16.2% — both falling short of market consensus by 8.7% and 10.6% respectively.
The culprit is delayed revenue recognition in the heavy industry division. Shipments destined for the Middle East have been disrupted by geopolitical risks, while deliveries to the United States have been pushed back because customers' substation sites are not yet ready to receive equipment. Crucially, this pattern is not new: similar delays plagued the second quarter as well, suggesting that short-term earnings volatility may be structurally larger than the market had assumed.
Fundamentals remain intact
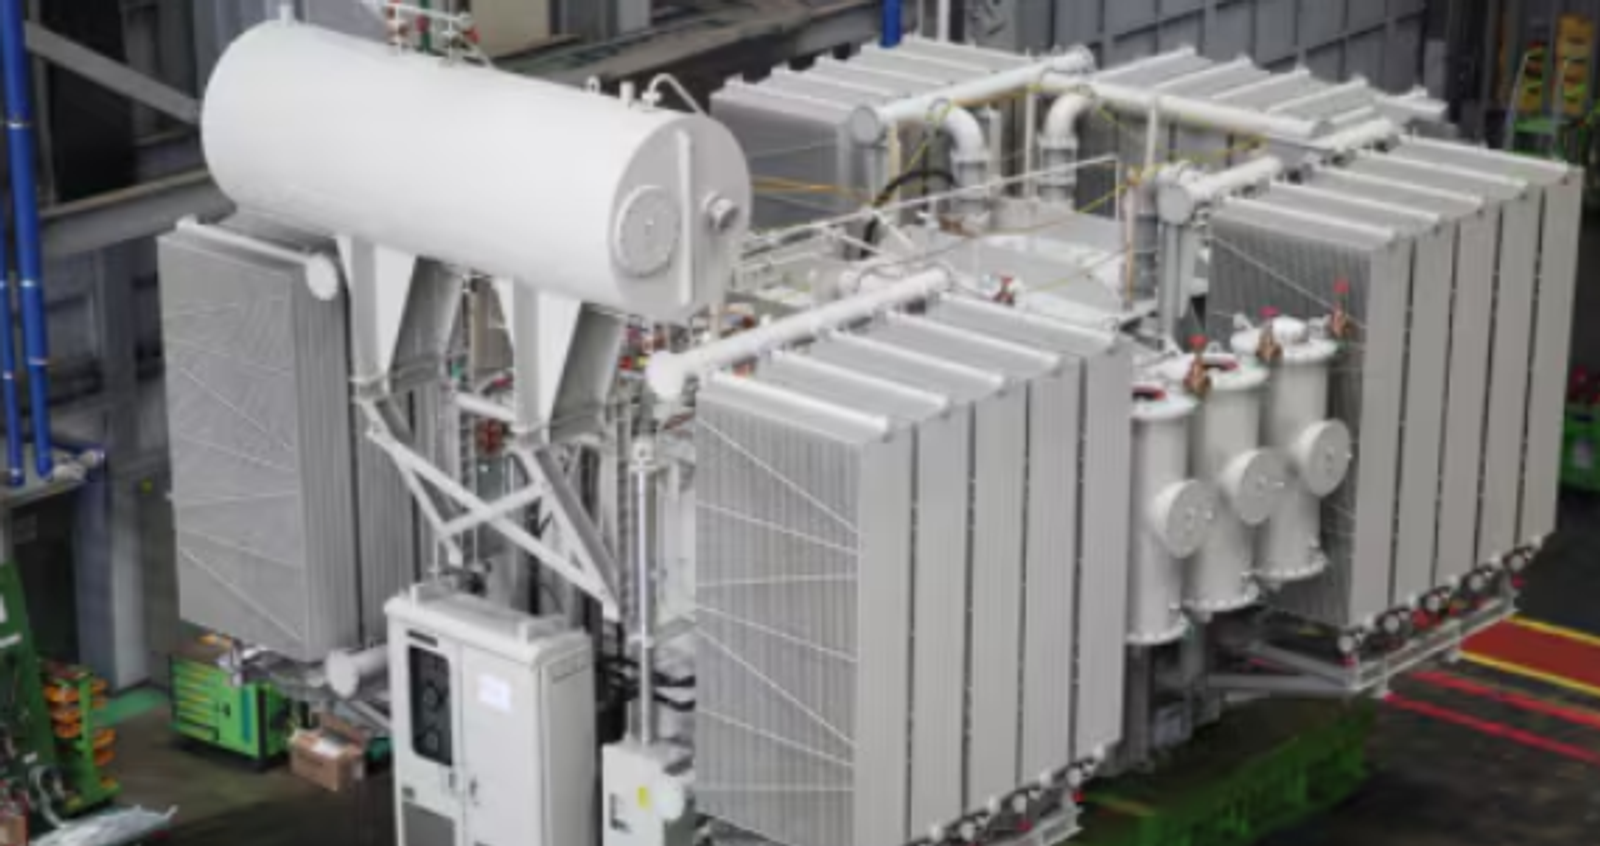
Mirae Asset is careful to distinguish between operational noise and structural deterioration. During the third quarter, Hyosung Heavy Industries secured an order worth ₩386.6bn for ultra-high-voltage transformers from an American hyperscaler — one of the giant data-centre operators such as Amazon, Microsoft or Google. That a hyperscaler, rather than a traditional utility, is directly procuring grid infrastructure is itself a notable shift in the industry's demand structure. As data-centre operators race to secure their own power supplies, Hyosung's ability to win such contracts underscores the resilience of its order pipeline.
A joint venture to anchor American ambitions
Over the medium term, the most significant growth catalyst is a joint venture with Quanta Services, a leading American transmission-grid engineering, procurement and construction (EPC) contractor. The partnership gives Hyosung Heavy Industries a domestic American manufacturing base for gas circuit breakers (GCBs), with production scheduled to begin in October 2026. Initially, finished components will be shipped from Korea for final processing and assembly in the United States; meaningful revenue contribution is expected from next year onwards. By pairing its transformer expertise with Quanta's EPC capabilities, Hyosung aims to broaden its offering beyond transformers into gas-insulated switchgear (GIS) and STATCOM systems — positioning itself as a provider of integrated power solutions rather than a single-product supplier.
The company also employs project-by-project currency-hedging strategies, which should limit the impact of exchange-rate fluctuations on the profitability of its existing backlog.
Financial forecasts
Mirae Asset projects full-year 2026 revenue of ₩6.6110tn, up 10.8% year on year, with operating profit of ₩984.0bn, up 32.4%. Growth is expected to accelerate thereafter: revenue of ₩7.6380tn and operating profit of ₩1.3550tn are forecast for 2027, rising to ₩8.9430tn and ₩1.8840tn respectively by 2028. Operating margins are seen improving steadily from 12.5% in 2025 to 21.1% by 2028.
The revised target price of ₩4.4m is derived by applying a price-to-earnings multiple of 28.9 times — the average 2028 consensus PER among global peers in the ultra-high-voltage transformer sector. Against the closing price of ₩2,242,000 on 12 October 2026, that implies potential upside of 96.3%.
Risks worth watching
Investors should not overlook several cautionary signals. The current share price sits at barely half its 52-week high of ₩4,601,000. The stock has lost 23.7% in absolute terms over the past six months and underperformed its benchmark by 15.4% over the past year. The target price itself has now been cut twice in quick succession — from ₩5m just three months ago in July 2026 to ₩4.4m today. If revenue recognition delays continue to recur quarter after quarter, consensus earnings estimates may face further downward pressure until the uncertainty over delivery timing is resolved.
Valuation and order-book context
On a relative basis, however, Hyosung Heavy Industries looks inexpensive. Its 2026 price-to-earnings ratio of 26.7 times is well below the peer-group average of 51.2 times for ultra-high-voltage transformer manufacturers, pointing to significant valuation headroom. The order backlog is expected to reach ₩28.5210tn by end-2026, a 16.9% increase from a year earlier, with the United States accounting for 57% of that total — a concentration that positions the company squarely in the path of surging North American grid-investment spending.
In the final analysis, near-term earnings noise matters less than two longer-term questions: whether Hyosung can sustain its order momentum, and how quickly its American local-production capabilities come fully on stream. The answers to those questions, rather than any single quarterly earnings miss, are likely to determine where the share price goes from here.